OFAC: The Treasury Office That Can Cut Nations Off From the Dollar
· Originally published by ontime+
The latest:
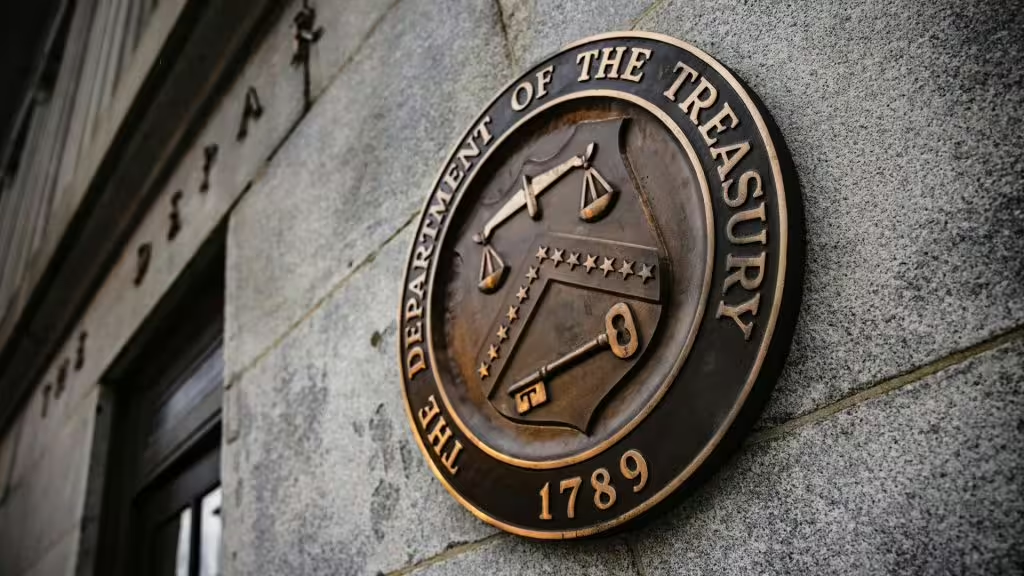
A single Treasury office, the Office of Foreign Assets Control, can freeze assets under US jurisdiction and bar American firms from dealing with any listed entity, effectively detaching banks, companies and states from the dollar system. Its reach extends far beyond US borders, because foreign institutions that depend on American correspondent banking often comply rather than risk losing access to the dollar.
Details:
- The mechanism: OFAC designates individuals, companies and institutions on sanctions lists, chief among them the Specially Designated Nationals list. Designation freezes assets under US jurisdiction and, in many cases, bars American persons and companies from any dealings with the target, cutting it out of the world’s largest financial market.
- Why it travels: Nearly every major international transaction in oil, shipping or technology passes at some stage through a US clearing bank. That structural position converts an administrative listing into a global exclusion order, since dollar clearing is the chokepoint almost no large cross-border deal can route around.
- Secondary sanctions: Washington rarely needs to penalize a foreign company directly to change its behavior. The prospect of losing access to the US financial system is often enough, and European and Asian banks weighing the American market against a sanctioned counterparty generally choose the former.
- The record fine: In 2014, OFAC reached a 963 million dollar settlement with BNP Paribas over transactions tied to sanctioned countries, part of a broader 8.9 billion dollar settlement with other US authorities after investigators concluded the bank stripped sanctions-related information from thousands of transactions routed through the United States.
- Recent activity: In the first months of 2026, OFAC announced seven enforcement actions and settlements totaling roughly 284.1 million dollars, including a 275 million dollar settlement with Adani Enterprises. The figures illustrate the pace of enforcement rather than its full deterrent weight.
- The Russian bank: In September 2026, OFAC targeted Russia’s VTB Bank over what the Treasury described as helping Iran evade sanctions, including correspondent relationships with sanctioned Iranian banks. Washington warned foreign financial institutions that dealing with designated entities could expose them to secondary sanctions, including restrictions on their US correspondent accounts.
- The Iran file: The Treasury says its operations target oil smuggling networks, financial channels and facilitators that help Tehran reach revenue. Sanctions reimposed on Iran’s energy sector have damaged foreign currency earnings, driven a sharp fall in the rial and pushed inflation to historic levels, according to the account under review.
- Preemptive compliance: Banks, insurers, shipping companies and energy traders often avoid transactions not because they are directly sanctioned, but out of fear a deal could breach OFAC rules or endanger their US financial relationships. That self-policing extends the office’s reach well past the names it actually designates.
- The workarounds: Moscow and Beijing treat OFAC as evidence of overreach and are building parallel settlement systems. Russia has deepened economic ties with Iran using non-dollar clearing, while private Chinese refiners buy discounted Iranian crude through an opaque tanker fleet, even as major Chinese banks stay cautious.
Background:
OFAC sits inside the US Treasury and enforces sanctions through presidential orders, blacklists and secondary measures. Its authority grew over the past decade as Washington leaned on economic instruments rather than military ones to pressure adversaries including Iran, Russia and their financial intermediaries.
Between the lines:
The BNP Paribas settlement and the VTB designation point the same way: enforcement lands hardest on intermediaries, not on the sanctioned state itself. That explains why Chinese refiners keep buying Iranian oil while Chinese banks stay out. The dependency runs through correspondent accounts, and institutions that need them comply even when their governments object. The parallel systems Moscow and Beijing are building wager that dependency can be reduced.
What’s next
Watch whether foreign banks curtail dealings with VTB after the secondary-sanctions warning, the pace of new Treasury designations against Iranian oil networks, and whether non-dollar settlement arrangements between Moscow and Tehran expand.